Tax Section
Transferee Liability Under Section 6901

In general, operating a business through an entity can provide limited liability in the event the entity is insolvent or goes out of business. Limited…
Taxation of Noncompete Agreements
Purchasers of a successful business have the reasonable concern that the prior owners will use their expertise to open a new business across the street that…
You Cannot be Both an Employee and a Partner of a Partnership
A person who is both an employee and a partner in a partnership is not treated as an employee for tax purposes. Rev. Rul. 69-184 states “bona fide members…
Wells Hall Becomes Chair of the ABA Section of Taxation
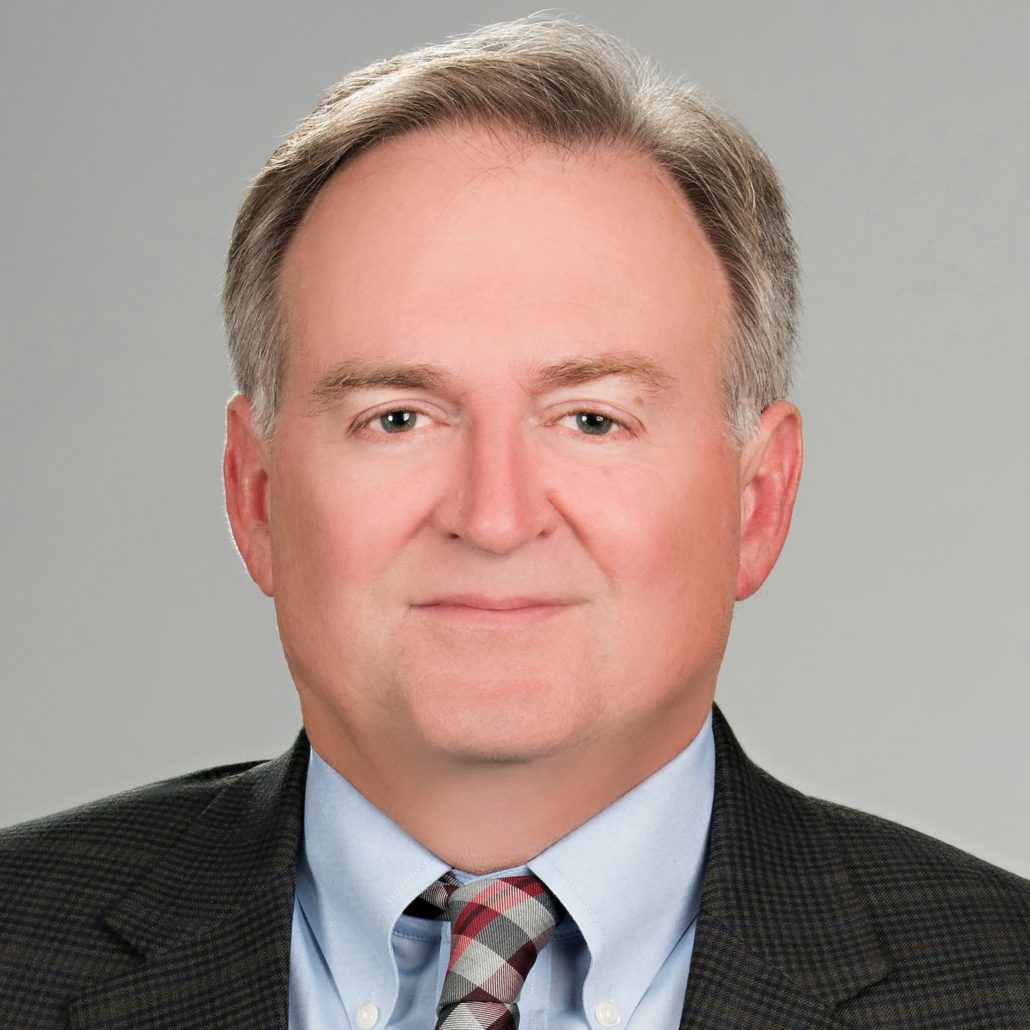
Our colleague Wells Hall is now the chair of the ABA Tax Section. Congratulations Wells! Wells is an attorney with Nelson Mullins and a long-time mainstay of…
What is an IC-DISC?
An interest charge domestic international sales corporation (“IC-DISC”) is a special tax exempted domestic corporation that qualifies under Sections 991…
The Basics of F Reorganizations
Among the tax-free reorganizations authorized by Section 368 is the F reorganization. Section 368(a)(1)(F) defines this type of reorganization as “a mere…
Remembering Bob Mendenhall
Bob Mendenhall, former Chair of the North Carolina Bar Association Tax Section, passed away on July 14, 2022, at the Charlotte Rehab Center, one day before…
What is an Investment Partnership?
As discussed in my January 12, 2022, blog post, Section 731(c) generally treats marketable securities as money in determining gain or loss on a distribution…
Quid Pro Quo: Charity Disclosure Requirements
Section 6115 imposes a disclosure requirement on charitable organizations that receive quid pro quo contributions in excess of $75. A quid pro quo…
Recent National Articles about North Carolina Tax Matters
There have been several recent national articles about North Carolina tax matters. 1. The May 11, 2022 issue of Taxes – The Tax Magazine has an article…